How Do I Know If My Rolex Is in Good Condition for a Loan?
It’s Friday night before a major auction weekend in Scottsdale. You have a Rolex in the safe, a purchase or business expense coming up, and you would rather not sell the watch—or spend days waiting on a bank. The practical question is not just whether the Rolex looks good. It is whether a lender can authenticate it, assess its condition and marketability, and offer terms that make sense for the cash you need.
A Rolex can be a liquid luxury asset, but “liquid” does not mean every model, in every condition, turns into cash at the same speed or value. For a rolex collateral loan, condition matters alongside model, reference, age, originality, completeness, and current buyer demand. Here is how to make a useful first assessment before you bring the watch in.
What “good condition” means to a lender
A lender is usually evaluating two things: whether the watch is genuine and what it could reasonably realize in the market if the loan is not repaid. A watch can be worn and still be acceptable collateral. It does not need to look fresh from a boutique. But visible wear, missing parts, uncertain service history, or modifications can affect the valuation and the amount a lender is willing to advance.
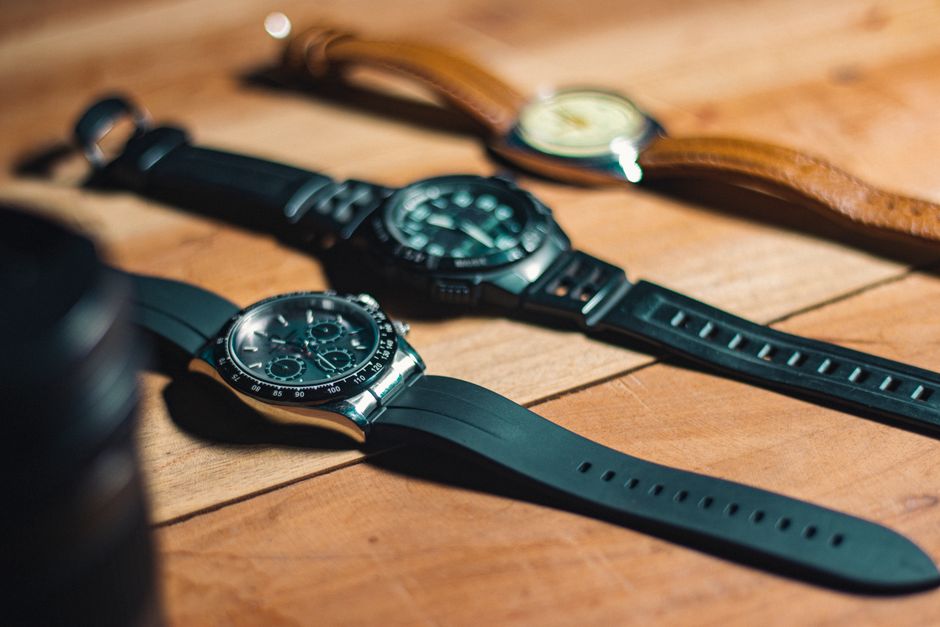
Condition is not a single grade that settles everything. A well-kept, less sought-after reference may be less useful collateral than a heavily worn example of a model with stronger demand. The lender considers the complete picture, then makes an offer under its own lending policies.
Start with these visible checks
- Case and lugs: Look for deep dents, cracks, heavy scratches, or signs that the case has been aggressively polished. Polishing can soften the original shape and edges.
- Bracelet and clasp: Check for a secure clasp, missing links, damaged screws, and excessive stretch. A loose bracelet may be repairable, but it can affect the condition assessment.
- Dial and hands: Note discoloration, moisture marks, loose markers, or hands that appear inconsistent with the model. Do not try to clean or alter anything yourself.
- Crystal and bezel: Cracks, chips, replacement parts, or damage to a rotating bezel can affect the watch’s condition and market appeal.
- Function: Does it wind, set, and run? Does the date change as expected? A watch that runs is not automatically healthy inside, and a watch that has stopped may still have collateral value—but servicing may be part of the picture.
- Moisture exposure: Fogging beneath the crystal, corrosion, or a musty smell deserves immediate attention. Avoid opening the watch to investigate.
These are screening observations, not a technical diagnosis. A Rolex’s movement, water resistance, and internal condition need appropriate examination. Don’t test water resistance at home, especially on an older watch or one with an unknown service history.
Originality, papers, and service history
Original components can matter. A replaced dial, bezel, bracelet, or set of hands may be perfectly legitimate, but the details should be disclosed. Some changes can reduce collector appeal; others may be routine service replacements. The effect depends on the exact reference and what the market values for that watch.
Gather anything that helps establish the the watch’s identity and history:
- Warranty card, certificate, or other original documentation, if available
- Box, manuals, extra bracelet links, and purchase paperwork
- Service receipts and records from a qualified watchmaker or service center
- Any information about replacement parts, repairs, or previous ownership
Missing papers do not automatically make a Rolex unsuitable for a loan. Nor does having a box and papers guarantee a higher advance. The watch itself still needs to be examined and authenticated. Be straightforward about what you know and what you do not know; a clear history is more useful than a confident guess.
Why watch authentication and valuation matter
A professional watch authentication review is more than checking the logo on the dial. The evaluator may compare the reference and serial details, inspect components and construction, assess whether parts are consistent with the model, and examine the watch’s operation. The exact process varies by top luxury loan scottsdale provider and by watch.
Valuation is a separate step. An appraisal is an opinion about value for a stated purpose; it is not necessarily the same as a loan offer or a guaranteed resale price. For collateral, the lender typically considers likely resale demand, condition, selling costs, risk, and how quickly the watch could be converted to cash. Ask what the valuation represents and how the loan amount is calculated from it.
In Scottsdale, someone searching for a watch appraisal Scottsdale should ask whether the appointment includes authentication, whether the watch is examined in person, what documents to bring, and whether there is a charge for the assessment. Also ask who holds the watch during review and how it is secured. Those are practical questions, not awkward ones.
Rolex liquidity: valuable does not mean instantly sellable
Rolex is widely recognized, and many models have active resale markets. Publicly visible asking prices, completed sales, dealer offers, and auction results can help show how global secondary market pricing is tracked publicly. But those figures are not interchangeable. An asking price is not proof that a buyer paid that amount, and an auction result may include buyer’s premiums, fees, or unusual bidding conditions.
Model and reference matter. So do dial configuration, metal, age, completeness, condition, and current demand. A common steel model with broad buyer interest may be easier to place than an unusual precious-metal or heavily modified example. Market conditions also change. A figure seen online last year—or even several months ago—may not describe what a lender can responsibly advance today.
That is the key distinction: a Rolex may be relatively liquid compared with many luxury goods, but a collateral loan is not the same as selling the watch. A lender is making a loan against the asset, and the cash offered will generally be shaped by risk and the lender’s need to recover funds if repayment does not happen.
What a Rolex collateral loan can do—and what it costs
A collateral loan can free cash while allowing you to retain the possibility of getting the watch back, subject to the loan agreement and repayment. It may suit someone who needs short-term liquidity but does not want to sell an heirloom or a watch they expect to wear again. It is not a bank credit line: the watch secures the debt, and the terms, fees, custody arrangements, and consequences of nonpayment are specific to the agreement.
Here is the tradeoff. A private, direct process can be faster and involve fewer steps than applying for conventional financing, depending on the provider and the watch. But speed and convenience do not mean the loan is inexpensive. Interest, fees, loan duration, renewal rules, and repayment requirements affect the real cost. Compare the total amount due by the date you expect to repay—not only the headline rate.
Question to ask Why it matters What is the total payoff amount, including fees? It shows the actual cost for your expected loan period. How long is the term, and can it be renewed? A short term may not fit your cash-flow timeline. Where and how is the watch stored? You should understand custody, security, and insurance arrangements. What happens if I miss the payoff deadline? The contract should explain default, extensions, and potential loss of the watch. Is the offer based on an in-person inspection? A preliminary estimate can change after authentication and condition review.Do not borrow more than you need simply because an offer allows it. Make sure the repayment plan is realistic. If you are unsure, compare the loan’s total cost with the net amount you might receive from a sale and with other available ways to raise cash.
Plan around auction week, not the auction-day rush
During a Barrett-Jackson week at WestWorld of Scottsdale, the area gets busy with collectors, visitors, and high-value purchases. That can make a watch loan feel timely: you may want funds available for a car, travel, a business obligation, or an opportunity that will not wait. But a crowded auction calendar is a reason to plan earlier, not assume a same-day deal.
Here's what kills me: schedule an assessment before you need to make a bid. Ask how long authentication and valuation usually take, whether an appointment is required, and when cleared funds could be available if you accept the terms. Timing depends on the watch, the provider’s process, and the documentation—not just the fact that it is auction week.
Companies such as Diamond Banc operate in the broader luxury-asset lending and buying space, but terms and services can vary by location and transaction. Speak directly with the provider about its current process, loan structure, security arrangements, and timeline. Do not assume an auction-week offer is automatically better because there are more collectors in town.
How to prepare for an appraisal appointment
- Bring the watch as it is. Do not polish the case, replace parts, or attempt a repair just to improve its appearance.
- Bring available records. Include papers, service receipts, purchase documentation, and spare links or parts.
- Write down what you know. Note when it was last serviced, whether it has been repaired, and any known damage or component changes.
- Ask for the process. Confirm how the watch is authenticated and valued, who handles it, and whether the review is completed on-site.
- Request written loan terms. Review the rate, fees, term, payoff amount, renewal options, and default provisions before signing.
- Take your time. If the offer is unclear or the repayment schedule feels tight, pause and compare alternatives.
Signs your Rolex may need extra review
Expect additional questions if the watch has a non-original dial or bracelet, aftermarket parts, missing or unclear serial information, moisture damage, a stopped movement, or a repair history you cannot verify. These issues do not always rule out a loan. They can, however, make authentication more involved or change the valuation and advance.
Likewise, a watch that looks excellent may still need internal service. Cosmetic condition is only one part of the assessment. A clean case and working seconds hand do not prove that the movement is healthy or that every component is correct for the reference.
The bottom line
You can make a useful first assessment by checking the case, bracelet, dial, crystal, function, and available records. But only an appropriate in-person review can establish authenticity and assess condition with confidence. For a Rolex collateral loan, the lender will also consider current demand and the practical resale market—not just what a similar watch is listed for online.
If you need cash around a Scottsdale auction weekend, start the process before the day you need sell vs borrow rolex to act. Compare written terms, ask how the authentication and valuation process works, and calculate the payoff for your actual timeline. A Rolex may offer meaningful liquidity, but the right decision depends on the watch, the loan cost, and whether you can comfortably repay it.