Is a Rolex Loan a Good Idea for a Short-Term Need?
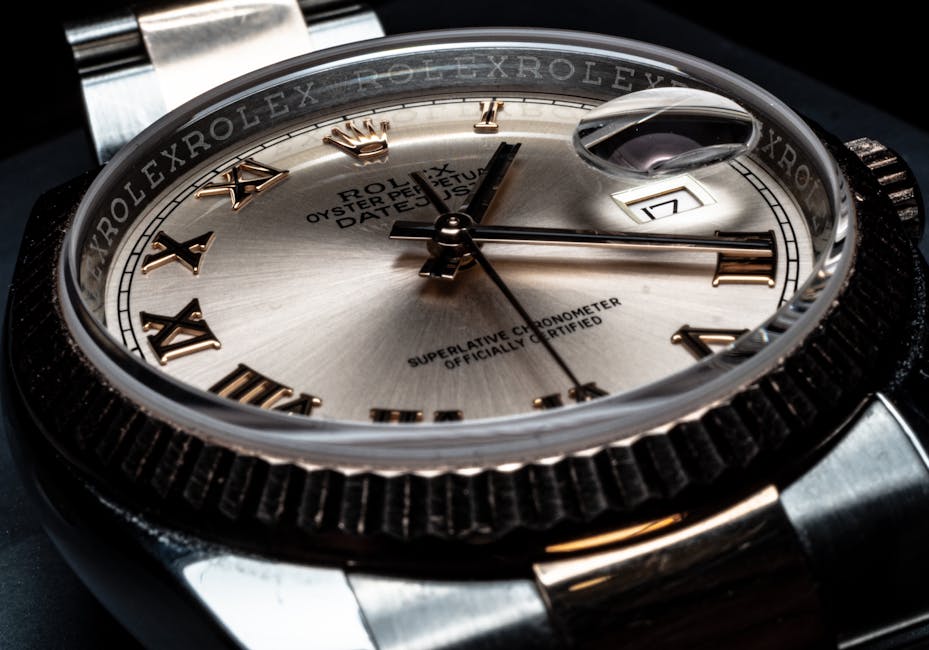
A Rolex can be more than something you wear. It can also be a valuable asset that may help cover a short-term cash need—without requiring you to sell the watch outright.
That can sound especially appealing in Miami, where an Art Week opportunity, a business expense, or a time-sensitive purchase may not wait for a slow sale or an investment account transfer. But a Rolex loan is still a loan. Borrowing costs money, and the watch’s resale value is not the same as the amount a lender will offer.
The decision comes down to timing, loan terms, and whether you have a realistic plan to repay. Here’s how to weigh borrowing against selling, what to check before handing over a watch, and when a Rolex loan may—or may not—make sense.
What Is a Rolex Loan?
A Rolex loan is generally a secured loan: you use your watch as collateral and receive money against its assessed value. The lender holds the watch while the loan is outstanding. If you repay the amount due under the agreement, you get the watch back. If you do not, the lender may have the right to sell it, subject to the contract and applicable law.
That arrangement can be attractive to an owner who needs cash briefly but wants to keep a particular watch. It may be less appealing if you need a large sum, have no dependable repayment source, or would be upset to lose the watch.
Not every Rolex is valued the same way. Model, reference, condition, age, originality, service history, box and papers, and current buyer demand can all matter. A watch’s retail price—or the price you paid—is not a reliable shortcut to its collateral value.
Why Rolex Can Work as Collateral
Rolex is a globally recognized brand with an active secondary market. That visibility can make some models easier to price and resell than less familiar luxury goods. For a lender, the ability to assess likely resale demand matters. For an owner, it means a watch may be a practical asset to consider when a temporary need appears.
But “liquid” does not mean “instant cash at full market price.” A lender has to account for the cost and risk of holding and reselling the watch. A loan offer may be lower than a public asking price, and an asking price is not proof that a buyer has paid that amount.
Use public, secondary-market price checks as a reference—not a promise. Compare the same reference and similar condition where possible. Check whether the displayed number is an asking price, a completed sale, or an estimate, and note when the data was updated. A two-tone model, loan against rolex a steel sports reference, and a dress watch can have very different demand patterns.
Loan or Sale: The Main Tradeoff
With a loan, you keep the possibility of reclaiming the watch, but you pay for the cash and take on a deadline. With a sale, you give up ownership, but you avoid loan interest and the risk of a missed repayment turning into a lost watch.
If you own an unworn Rolex that no longer suits your taste, selling may be the cleaner choice. The money could fund a better fit: a different size, a more comfortable bracelet, a watch you will actually wear, or another priority altogether. There is no prize for holding an asset you do not want simply because it is a Rolex.
On the other hand, if the watch has personal meaning or would be difficult to replace, a short-term loan may be worth comparing—provided the repayment is dependable and the total cost is acceptable.
Choice What you get Main tradeoff May fit when Rolex loan Cash now, with a chance to reclaim the watch Interest, fees, a repayment deadline, and risk to the watch The need is temporary and repayment money is expected on a clear date Sell the watch Cash without a loan balance You give up the watch and may not be able to replace it at the same price You do not wear it, want a different watch, or do not want repayment pressure Wait or use another source A chance to avoid pledging or selling the watch The opportunity may pass, or the alternative may have its own cost The purchase is optional, the deadline can move, or another source is cheaperWhen a Rolex Loan May Make Sense
A loan is more plausible when the need is genuinely short-term, the repayment source is specific, and the watch matters enough that you would rather retrieve it than sell it.
- You can name the repayment source. For example, a confirmed invoice payment or a known cash inflow—not simply “I’ll figure it out.”
- The deadline is realistic. You have time to repay before the contract deadline, with room for ordinary delays.
- The total cost is clear. You know the interest, fees, renewal terms, and amount required to get the watch back.
- The loan is smaller than your need allows. You borrow only what covers the actual gap, rather than treating the watch’s value as permission to spend more.
- You accept the downside. If repayment fails, losing the watch would be painful but not financially devastating.
The key test is simple: borrow only what you can repay. A lender’s maximum offer is not a budget recommendation. If repayment depends on another loan, a speculative investment gain, or a sale you have not arranged, the plan is fragile.
When Selling May Be the Better Move
Selling can be more straightforward when you already know you want a different watch or you rarely wear the one you own. It removes interest and a repayment clock. It can also prevent a temporary cash need from becoming a longer, more expensive problem.
That does not mean selling is always easy. You will want to compare offers, understand any selling costs, and decide whether the amount you can actually receive makes the trade worthwhile. A dealer’s offer, a private buyer’s offer, and an online listing price are not interchangeable.

If the Rolex is unworn, consider the question plainly: would you rather keep this exact watch, or turn it into money for a better fit? If the answer is “better fit,” selling may align with what you want instead of paying to postpone the decision.
Here's what kills me: for some people, using a watch loan can feel cleaner than selling investments, particularly if they are trying to avoid disrupting a long-term portfolio. But compare the real costs. A loan can be expensive, while selling investments may have tax consequences, transaction costs, or other tradeoffs. Neither option is automatically superior. Look at the numbers and your timeline.
Art Week: Buying Power Meets a Hard Deadline
During Miami Art Week, a desirable work, a design piece, or a limited-run object can come with a “held until Sunday” deadline. A Rolex may seem like a way to unlock buying power without liquidating other assets or waiting for a watch sale to close.
That urgency is exactly why it helps to decide in advance. A deadline can make an expensive choice feel inevitable. It is not. Before pledging a watch for an Art Week purchase, ask whether the opportunity is worth both the purchase price and the loan cost—and whether repayment will still work if the work is delayed or an expected payment arrives late.
Do not borrow the maximum just because the event is temporary. If the purchase only works by adding debt you cannot comfortably repay, the deadline does not make it affordable. A missed opportunity is usually easier to recover from than a prized watch lost through a rushed decision.
In Coral Gables or elsewhere in Miami, arrange an appointment with a reputable business rather than taking an expensive watch to a parking lot meetup. Keep the watch in your possession until you are at a secure, professional location and understand the process.
What to Check Before You Agree
Ask for the complete terms in writing. Do not settle for a quick verbal summary of the amount you can receive. Compare the cash you get today with the full amount required to redeem the watch on the date you expect to repay.
- Ask how the watch is valued. Request an explanation of the reference, condition, and comparable market data used.
- Check public secondary-market pricing. Look for recent, relevant comparisons. Separate completed sales from listings, and compare like with like.
- Get the all-in repayment figure. Include interest, fees, storage charges if any, and any costs tied to late payment or renewal.
- Confirm the deadline and grace period. Ask what happens if payment arrives one day late, and whether an extension is available or guaranteed.
- Understand what happens after default. Read the rules for notice, sale of the watch, and any remaining balance or surplus.
- Document the watch’s condition. Record the reference and serial number appropriately, photograph the watch, and note included accessories.
- Use a secure, professional handoff. Get a receipt identifying the watch and confirming what the business is holding.
Ask whether authentication and valuation happen on-site, who performs them, and what inspection includes. An on-site process can make the assessment easier to follow because you can ask questions while the watch is being examined. It does not replace reading the contract or verifying the business’s credentials and procedures.
I remember a project where thought they could save money but ended up paying more.. If the watch has been modified, polished, serviced, or is missing parts or papers, disclose that up front. Surprises discovered during inspection can change an offer. Do not assume box and papers automatically create a particular premium; ask how they affect this specific assessment.
A Simple Cost Check
Suppose you borrow $8,000 for 30 days. For illustration only, if the interest were 5% for the period, the interest alone would be $400, before any fees. The actual rate structure and fees can differ substantially by provider and agreement. Ask for the precise dollar amount due, not just a percentage that sounds small.
Then compare that cost with the alternatives. What would a sale net after any selling costs? What would it cost to buy a comparable replacement later? What are the consequences of selling investments or using another form of credit? The answer may favor a loan, a sale, or neither. The point is to make the tradeoff visible before the deadline.
Also test the repayment plan against a delay. If your expected money arrives two weeks late, can you still repay without extending the loan or missing another bill? If not, the plan may be too tight for a luxury purchase or an optional expense.
A Practical Decision Checklist
Before you pledge a Rolex, answer these questions honestly:
- Is the cash need temporary, and do I know exactly when it ends?
- What is the specific source of repayment?
- What is the total dollar cost to get my watch back?
- Can I repay even if my expected payment is delayed?
- Would I rather sell this watch and put the proceeds toward something I will wear?
- Am I borrowing for a necessity, a business need, or a time-sensitive want?
- Would I be comfortable if I did not recover the watch?
If the last answer https://technivorz.com/should-i-bring-service-records-to-sell-my-rolex/ is no, take extra care. A loan secured by something emotionally important carries more than a financial cost.
The Bottom Line
A Rolex loan can be a useful short-term tool when you have a clear repayment plan, understand every charge, and value keeping the watch more than avoiding the borrowing cost. A recognized brand and an active secondary market may help with valuation, but they do not guarantee a high offer or an easy exit.
If the watch is unworn and you want a different one, selling may be the more direct move. If the need can wait, waiting may be cheapest. And if Art Week has a piece held until Sunday, remember: urgency is not a repayment plan.
Compare public market data, ask for authentication and valuation on-site, read the written terms, and borrow only what you can repay. The right choice is the one that still feels manageable after the deadline passes.